Last Updated: November 15, 2026
Quick Summary
Moving insurance for antique furniture should cover the piece’s actual value, not just its replacement cost in a store. Standard mover coverage is often too limited, so antique owners should compare coverage levels, declare high-value items in writing, and document condition before the move.
- Standard moving coverage is built for ordinary household goods, not high-value antiques.
- Full-value protection requires the mover to repair, replace or pay the declared value.
- Released value is the cheapest option but offers the least protection for antiques.
- Declaring a value below the appraisal can leave you underpaid when you file a claim.
- Photograph and record each antique’s condition before moving, and keep the report with your appraisal.
Table of Contents
- Why Antique Furniture Needs Different Moving Insurance
- Released Value, Basic Valuation and Full-Value Protection Compared
- Mover Liability for Damaged Furniture vs. Insurance
- Antique Furniture Appraisal for Insurance: Establishing Value
- How to Document Furniture Condition Before Moving
- Packing Antiques for Moving and Exclusions to Watch For
- Booking Your Move With Full Coverage Questions Answered
- Frequently Asked Questions
Why Antique Furniture Needs Different Moving Insurance
Standard moving coverage is built around ordinary household goods, and that is where many antique owners get caught out.
Before booking, read the coverage terms and ask your mover how they handle items they do not know the value of.
Antiques also tend to be fragile in ways a standard policy does not account for. Old joinery, veneer, finishes and glass can be damaged by temperature and humidity swings in a truck, not just by impact.
Released Value, Basic Valuation and Full-Value Protection Compared
Movers commonly offer a small number of coverage levels.
Released value is typically the lowest-cost option and the least protective.
Full-value protection requires the mover to repair, replace or pay the actual value of a damaged item, up to the declared amount.
Here is how the three options compare:
| Coverage level | Mover’s liability | Typical cost | Best for |
|---|---|---|---|
| Released value | Low, per pound per item | Lowest | Replaceable, low-value furniture |
| Basic valuation | Limited, by weight or declared value | Moderate | Mixed household goods |
| Full-value protection | Repair, replace or pay declared value | Highest | Antiques and high-value pieces |
Costs and coverage limits differ between movers, so ask for the exact terms in writing and confirm them against your own valuation.
Declared value vs. full-value replacement: pros and cons
- Declared value gives a clear ceiling you set yourself. It is easy to understand, but if you declare too low, you will be underpaid on a claim.
- Full-value replacement commits the mover to restoring or replacing the item. It is more protective, but it usually carries a higher premium and may require a detailed inventory.
Mover Liability for Damaged Furniture vs. Insurance
Mover liability and insurance are not the same thing. Mover liability is the legal responsibility a moving company accepts for damage it causes.
In practice, a claim against the mover depends on proving the mover caused the damage and documenting the item’s condition beforehand. Without that evidence, a claim can stall.
It is worth checking your homeowner or tenant policy before the move.
Antique Furniture Appraisal for Insurance: Establishing Value
Coverage is only as good as the value on record, and for antiques the number on record is rarely obvious. A piece can be worth far more, or far less, than its original purchase price, and insurers and movers will not accept a figure you cannot support. A defensible valuation also depends on the purpose of the appraisal, since valuing antiques for sale may call for a different approach than documenting replacement value for moving coverage.
What an appraisal actually establishes
A qualified appraiser typically reports one of several value standards, and the standard matters as much as the number:
- Fair market value, what the piece would sell for between a willing buyer and seller, neither under pressure. This is the most common standard for insurance scheduling.
- Replacement value, what it would cost to buy a comparable piece in today’s market. This is usually higher than fair market value and is the figure full-value protection tends to require.
- Liquidation or forced-sale value, what it would fetch under time pressure. Rarely appropriate for insurance, but worth knowing so you can spot it if a report uses it.
Ask the appraiser which standard they applied and confirm it matches what your mover’s full-value protection or your homeowner rider requires. A report that states replacement value but is used to support a fair-market-value policy will leave a gap at claim time.
What a usable appraisal report contains
The report itself should be more than a one-line number. A report you can rely on in a claim generally includes:
- The appraiser’s name, signature, credentials and date of inspection
- A full description of the piece: maker or attribution, period, materials, dimensions, and distinguishing marks
- Photographs of the piece, including maker’s marks, joinery, hardware and any damage or restoration
Keep the original report and a scanned copy. If the piece is damaged, the report is the document that anchors your claim.
Supporting documents when a formal appraisal is not practical
Not every antique justifies a paid appraisal before a move. Where a formal report is not practical, build a file from what you have:
- Purchase receipts, auction records or dealer invoices showing what you paid and when
- Comparable sales, recent auction results or dealer listings for similar pieces, printed or saved with dates
- Provenance documents: previous family records, bills of sale, exhibition or restoration history
A common pattern is for owners to rely on an old appraisal that predates a market shift. If your only valuation is more than a few years old, ask the appraiser whether an update is warranted before you set a declared value.
Matching declared value to the coverage you buy
Once you have a valuation, reconcile it against the mover’s terms before booking. Most movers set a per-item or per-shipment limit above which an item must be specifically declared, and full-value protection is usually capped at the declared amount.
Watch out: declaring a low value to reduce the premium is the most common way antique owners end up underpaid, the mover will pay against the declared figure, not the appraisal, so the savings on the premium can be dwarfed by the shortfall on a claim.
When to get the appraisal done
Get the appraisal before you book coverage, not after. The sequence that works is: inventory the pieces, obtain or update valuations, declare high-value items to the mover in writing, then confirm the coverage level against those declared amounts. An appraisal obtained after the move cannot retroactively raise a limit you already agreed to.
How to Document Furniture Condition Before Moving
Documenting condition before the move is one of the most useful things you can do. Insurers and movers rely on it when assessing pre-existing damage versus damage during transit.
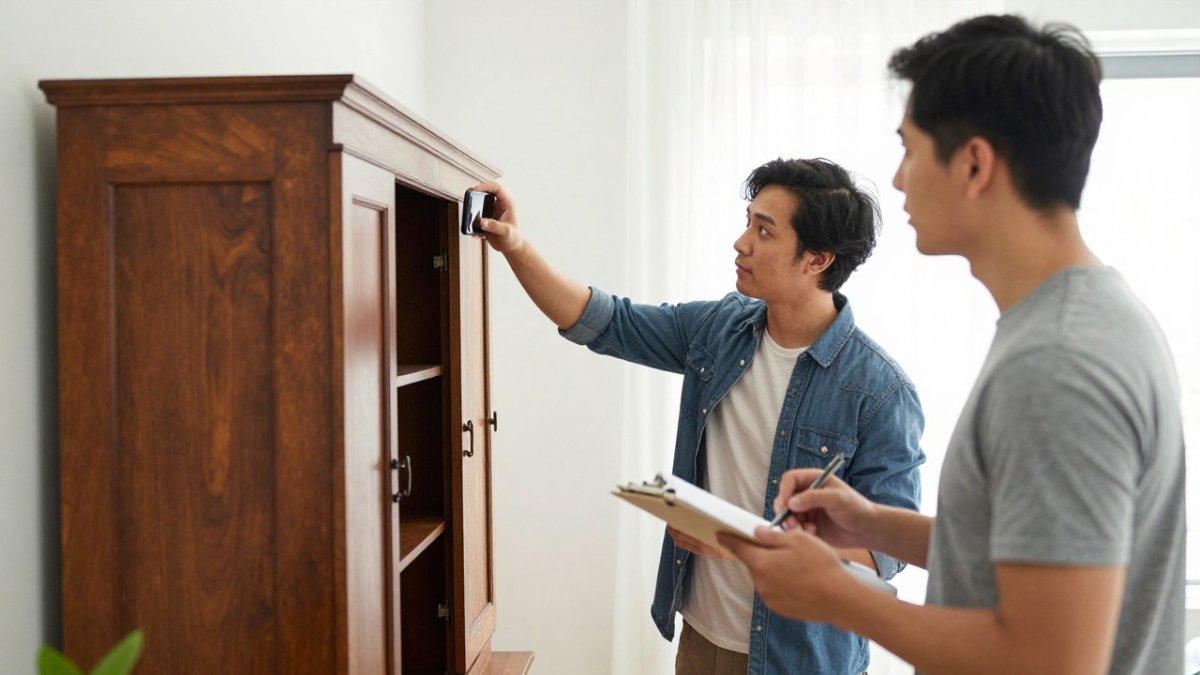
Use this checklist before moving day:
- Photograph each antique from all sides, in good light
- Close-up photos of joints, veneers, finishes, hardware and any existing cracks or chips
- Record measurements and weight where possible
Keep this evidence with your appraisal and receipts. If a claim is needed, it will be much easier to show what the piece looked like before it was loaded.
Packing Antiques for Moving and Exclusions to Watch For
Professional packing reduces the chance of damage, but packing alone does not decide whether a claim is paid. If you want experienced hands on delicate pieces, you can book professional packing services directly. The exclusions in the coverage terms do. Read both together, because a mover can exclude damage from packing it did not perform, and a specialist policy can exclude damage from packing that was not done to its standard.
Packing that supports a claim
Good packing is also evidence. Wrap wood surfaces in acid-free paper or felt, use corner protectors on tables and cabinets, and secure drawers and doors so they cannot slide open.
If you use the mover’s packing service, confirm in writing what the packing covers, whether materials are included, and, critically, whether the mover’s coverage responds to damage to items it packed.
Reading the exclusions that matter for antiques
Most exclusions are standard, but a handful hit antiques disproportionately. Check the wording for each of the following:
- Pairs-and-sets clauses. If a piece is part of a pair or set, a matched pair of chairs, a dining set, some policies pay only the value of the damaged piece, not the loss in value to the set. Ask whether the policy pays for the pair or set as a unit.
- Pre-existing damage and prior repairs. Wear, cracks, old repairs and restored finishes are commonly excluded. Your condition report is what separates pre-existing from transit damage.
- Inadequate or customer packing. Damage attributed to packing the mover did not perform is often excluded. Confirm who packs and whether that packing is covered.
Repair, replacement and diminution in value
The repair-versus-replacement term is where antique claims most often diverge from expectations. A policy that pays for repair may restore the piece physically but leave it worth less than before the damage, the loss in value is called diminution. Check whether the policy addresses diminution, and whether it pays the difference or treats repair as full settlement. If the wording is silent, ask the mover or insurer to confirm in writing how a repaired antique is valued at claim time.
A short pre-signature check
Before you sign or pay a deposit, take the coverage terms and mark each exclusion above as either addressed or silent. Anything silent is a question for the mover in writing. A short call to confirm exclusions before the move is far cheaper than discovering them after a loss, and written answers give you a record if a claim is later disputed.
Booking Your Move With Full Coverage Questions Answered
When you book, ask these questions and get the answers in writing:
- What coverage level is included in my quote, and what does it cost to upgrade?
- How do you handle items with a declared value above a set limit?
- Does the price include packing, stairs and truck time, or are those extra?
- What evidence do you require before a damage claim is accepted?
- How long do I have to file a claim after delivery?
- Can my own homeowner policy or a specialist policy cover items the mover does not?
Mansa Movers uses an all-inclusive hourly rate, and pricing depends on quantity, dates and delivery. For current prices or a quote tailored to your antiques and route, visit the Mansa Movers website to get your free moving quote.
Frequently Asked Questions
Does moving insurance cover antique furniture?
Standard moving coverage often pays only a set amount per pound unless you choose a higher valuation option, which can leave antiques badly underpaid. Released value coverage, the usual default, typically compensates at a fixed rate per pound, so a $5,000 cabinet could receive a payout far below its worth. Full-value protection, which carries a higher premium, is designed to replace or repair items at their declared value. Ask your mover in writing which option applies, what the deductible is, and whether antiques are excluded. If the coverage terms are unclear, a specialist or homeowners policy may fill the gap.
Is a mover’s liability the same as moving insurance?
No. Mover liability is the legal responsibility a moving company carries for damage caused by its own negligence, and it is usually capped by the valuation option you selected. Moving insurance, whether bought through the mover or a separate policy, is a contract that pays out when a covered loss occurs, sometimes regardless of fault. Liability limits can be far lower than an antique’s real value, so review both the mover’s liability terms and any additional coverage before the truck is loaded. Keep copies of the bill of lading and any valuation declarations for claims.
How do I determine the value of antique furniture before a move?
Start with a written appraisal from a qualified appraiser who can state the item’s replacement value or market value, which insurers and movers may require as proof. Gather purchase receipts, provenance records, photographs, and any previous insurance schedules. Note the maker, period, materials, and condition, since these drive value. Declare the value to your mover in writing before the move, and update the figure if the item is restored or its market changes. An appraisal typically needs to be current, so schedule it close to your moving date.
What should I do if movers damage an antique?
Photograph the damage immediately, before anything is moved or repaired, and note it on the delivery paperwork before signing. Report the claim to the moving company in writing within the deadline stated in your contract, and include your condition report, appraisal, and photos. Keep the damaged item in its current state until the claim is assessed, and get written repair estimates from a qualified restorer if repair is the proposed remedy. If the mover disputes the claim, escalate to your insurer or seek advice from a consumer protection office before accepting a settlement.
